Ontario Fall Market: A Buyer’s 2026 Playbook
September 29, 2026

Introduction
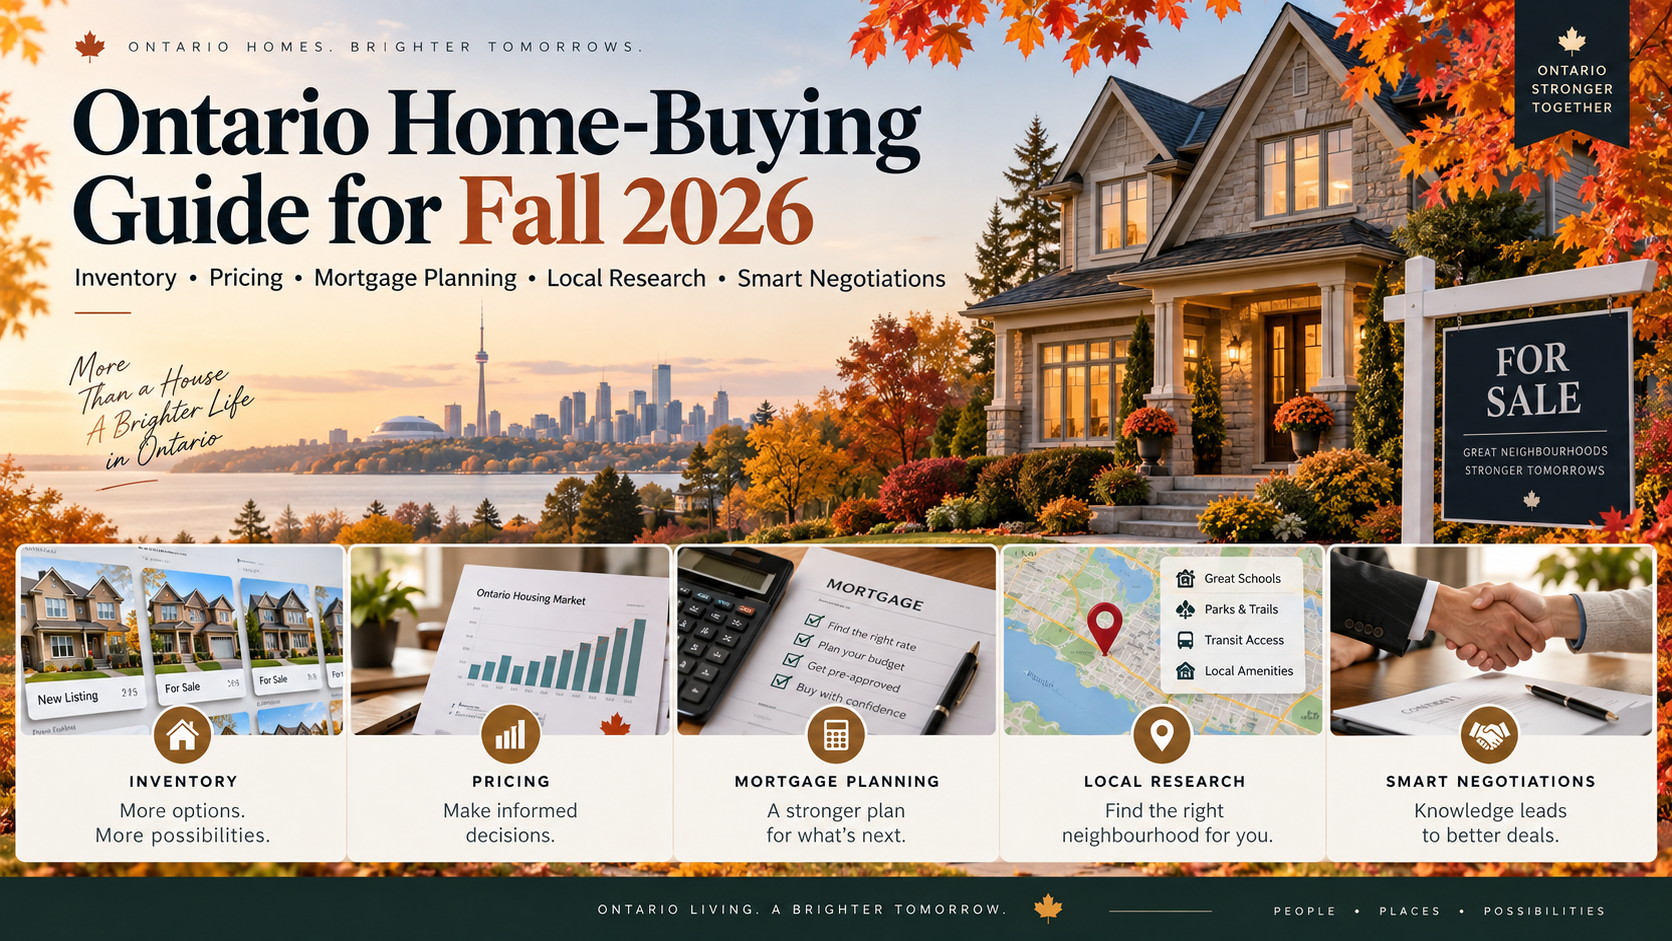
Ontario’s fall market can reward prepared buyers. After the spring rush and before the holiday slowdown, new listings often give purchasers more homes to compare, while sellers become more focused on completing a move before year-end. But Ontario is not one market. Conditions in Toronto can differ sharply from those in Ottawa, Hamilton, Kitchener-Waterloo, Durham, Niagara, Barrie, London, and smaller communities. A useful fall strategy starts with local evidence, a realistic financing plan, and the discipline to buy the right property rather than simply the first available one.
In fall 2026, buyers should avoid broad headlines such as “prices are rising” or “the market is soft.” Those statements may be true for a particular property type, price range, or neighbourhood, yet unhelpful for your search. Instead, track the segment you intend to buy: for example, a two-bedroom condo near transit, a freehold townhouse in a specific school catchment, or a detached home within a defined commute. This playbook explains how to read the market, prepare your mortgage, assess listings, and negotiate with confidence.
1. Read the Local Market, Not the Provincial Headline
The most relevant market data is narrow. Ask your REALTOR® for recent comparable sales from the last 30 to 90 days, active listings that directly compete with your target home, and listings that were cancelled, expired, or relisted. Sold prices show what buyers actually paid; active listings reveal the seller competition you face; failed listings can expose pricing that the market rejected.
Pay attention to months of inventory, average days on market, sale-to-list-price ratios, and the number of new listings versus sales. None of these metrics is a command to act, but together they describe leverage. More selection, longer selling times, and frequent price reductions can give buyers room for conditions or price discussions. Fast sales, few comparable listings, and repeated competing offers call for faster due diligence and a clearly defined maximum price.
- Compare like with like: condo to condo, freehold to freehold, and similar bedrooms, condition, parking, and location.
- Separate the asking price from market value. A low list price may be an offer-date strategy, while a high list price may simply be aspirational.
- Review micro-location factors, including transit access, school boundaries, planned construction, flood risk, traffic, and nearby amenities.
- Track a shortlist weekly. Note price changes, conditional versus firm sales, and how long comparable homes take to sell.
“A home is worth what a qualified buyer can justify from comparable evidence, not what a listing price or a headline suggests.
2. Get Mortgage-Ready Before You Fall in Love With a Home
Mortgage rates influence affordability, but the advertised rate is only one part of the decision. Your borrowing capacity also depends on income, debts, credit profile, down payment, property taxes, condominium fees, heating costs, and the lender’s qualification rules. A rate change can alter your budget, yet stretching to the top of a pre-approval can leave little room for repairs, moving costs, or future payment changes.
Speak with a mortgage professional early and request a written pre-approval or pre-qualification explanation that identifies the rate hold period, assumptions, and documents still required. Confirm how overtime, bonuses, self-employment income, rental income, student loans, car payments, and credit-card balances will be treated. Keep employment, deposits, and credit activity stable while your purchase is underway; a new loan, large unexplained transfer, or job change can affect final approval.
Build an all-in ownership budget. In addition to the down payment and mortgage payment, account for land transfer tax, legal fees, title insurance, appraisal costs if required, moving, utilities, insurance, immediate repairs, and a contingency reserve. First-time purchasers may qualify for applicable rebates, but eligibility and amounts depend on current rules and the purchase details. Verify them with your lawyer, lender, or qualified tax professional rather than relying on an old online estimate.
- Set a purchase ceiling below your lender’s maximum approval.
- Ask for payment examples at several interest-rate scenarios and amortization options.
- Keep proof of down payment and closing funds organized and traceable.
- Do not waive financing protection merely to make an offer appear stronger unless you fully understand and can absorb the risk.
3. Use Fall Inventory to Compare Quality, Not Just Price
Fall can bring households trying to complete a move before winter, owners testing the market after summer, and listings that did not sell in spring. That mix can create useful choice, but it also requires careful comparison. A polished listing may hide costly ownership issues, while a less glamorous home with sound systems, reasonable carrying costs, and a strong location may offer better long-term value.
Create a scorecard before viewings. Rate each property on location, layout, light, noise, parking, storage, monthly carrying cost, renovation needs, resale appeal, and deal-breakers. For houses, inspect the age and apparent condition of the roof, windows, heating and cooling equipment, electrical panel, drainage, foundation, and insulation. For condominiums, review the status certificate with a lawyer or experienced advisor. Pay close attention to the reserve fund, budget, insurance deductibles, pending litigation, rules, special assessments, and any major work planned for the building.
Do not let seasonal presentation distort your judgment. Leaf-covered grading can conceal drainage issues, early darkness can make a home feel dimmer than it is, and autumn weather can reveal drafts or moisture concerns. Visit at different times if possible. Walk the street, test the commute, and check the surroundings on a weekday evening as well as during an open house.
4. Make Offers That Protect You and Still Compete
A strong offer is not automatically the highest price. It is a clear proposal with terms the seller can realistically accept. Before writing, ask what matters to the seller: closing date, deposit timing, included chattels, flexibility, or certainty. Your representative can gather context from the listing side, but assumptions should never replace written terms and proper due diligence.
In a balanced or slower segment, conditions can be sensible risk management. Financing, home inspection, status certificate review, insurance availability, and sale-of-property conditions each serve different purposes. Their wording, timelines, and feasibility should be specific. A vague condition can create conflict; an overly short timeline can leave you unable to investigate properly. Consult your REALTOR®, lender, lawyer, inspector, and insurer as appropriate before removing conditions.
When competition is intense, decide your walk-away number in advance using comparable sales and your all-in budget. Escalation clauses, pre-emptive offers, and condition-free bids may be discussed in some situations, but each carries risks. Avoid bidding based on fear of missing out. Another listing will arrive; an overextended payment or an undiscovered defect can last much longer than a disappointing weekend.
- Use a meaningful deposit amount that you can deliver on the required schedule.
- Confirm inclusions such as appliances, window coverings, sheds, parking spaces, lockers, and rental equipment in writing.
- Price repair concerns using credible estimates rather than informal guesses.
- Keep communications professional and let the paperwork, comparables, and clean terms support your position.
5. Plan for Closing and the First Year of Ownership
An accepted offer begins a new phase. Meet deadlines promptly, provide documents requested by your lender, arrange home insurance, and retain an Ontario real estate lawyer early. Your lawyer will review title, closing adjustments, and the agreement details. If the property has rented equipment, verify contracts and costs. If you are buying a condo, understand occupancy, parking, locker, and management arrangements before closing.
Reserve money and time for the first year. Prioritize safety, water management, heating, locks, and essential maintenance before cosmetic upgrades. Keep records for warranties, inspections, invoices, and utility accounts. For a condo, attend meetings or read meeting materials to understand building decisions. For a house, establish seasonal routines for eavestroughs, filters, exterior drainage, and winter preparation. A purchase that fits your life and cash flow is more valuable than one that merely wins a bidding contest.
Conclusion: Let Preparation Create Your Advantage
Ontario’s fall 2026 market offers opportunity for buyers who replace urgency with process. Define your target area and property type, watch local comparable evidence, arrange financing before shopping, inspect the true cost of ownership, and use offer terms deliberately. Markets can change quickly, but the fundamentals do not: buy within a resilient budget, investigate what you are purchasing, and negotiate from facts. With that approach, fall inventory becomes more than a collection of listings—it becomes a better chance to find a home that works for the years ahead.
Comment (0)
Leave a comment
Your email address will not be published. Required fields are marked *
GET IN TOUCH
Have a question or need assistance? Reach out to us and we'll get back to you as soon as possible.
Contact us
We will respond at the earliest opportunity.
Information is deemed reliable but not guaranteed. Sourced in part from the Toronto Regional Real Estate Board (TRREB). Provided solely for consumers with a bona fide interest in the purchase, sale, or lease of real estate. Unauthorized use, reproduction, or distribution is strictly prohibited.